It usually happens around three in the morning.
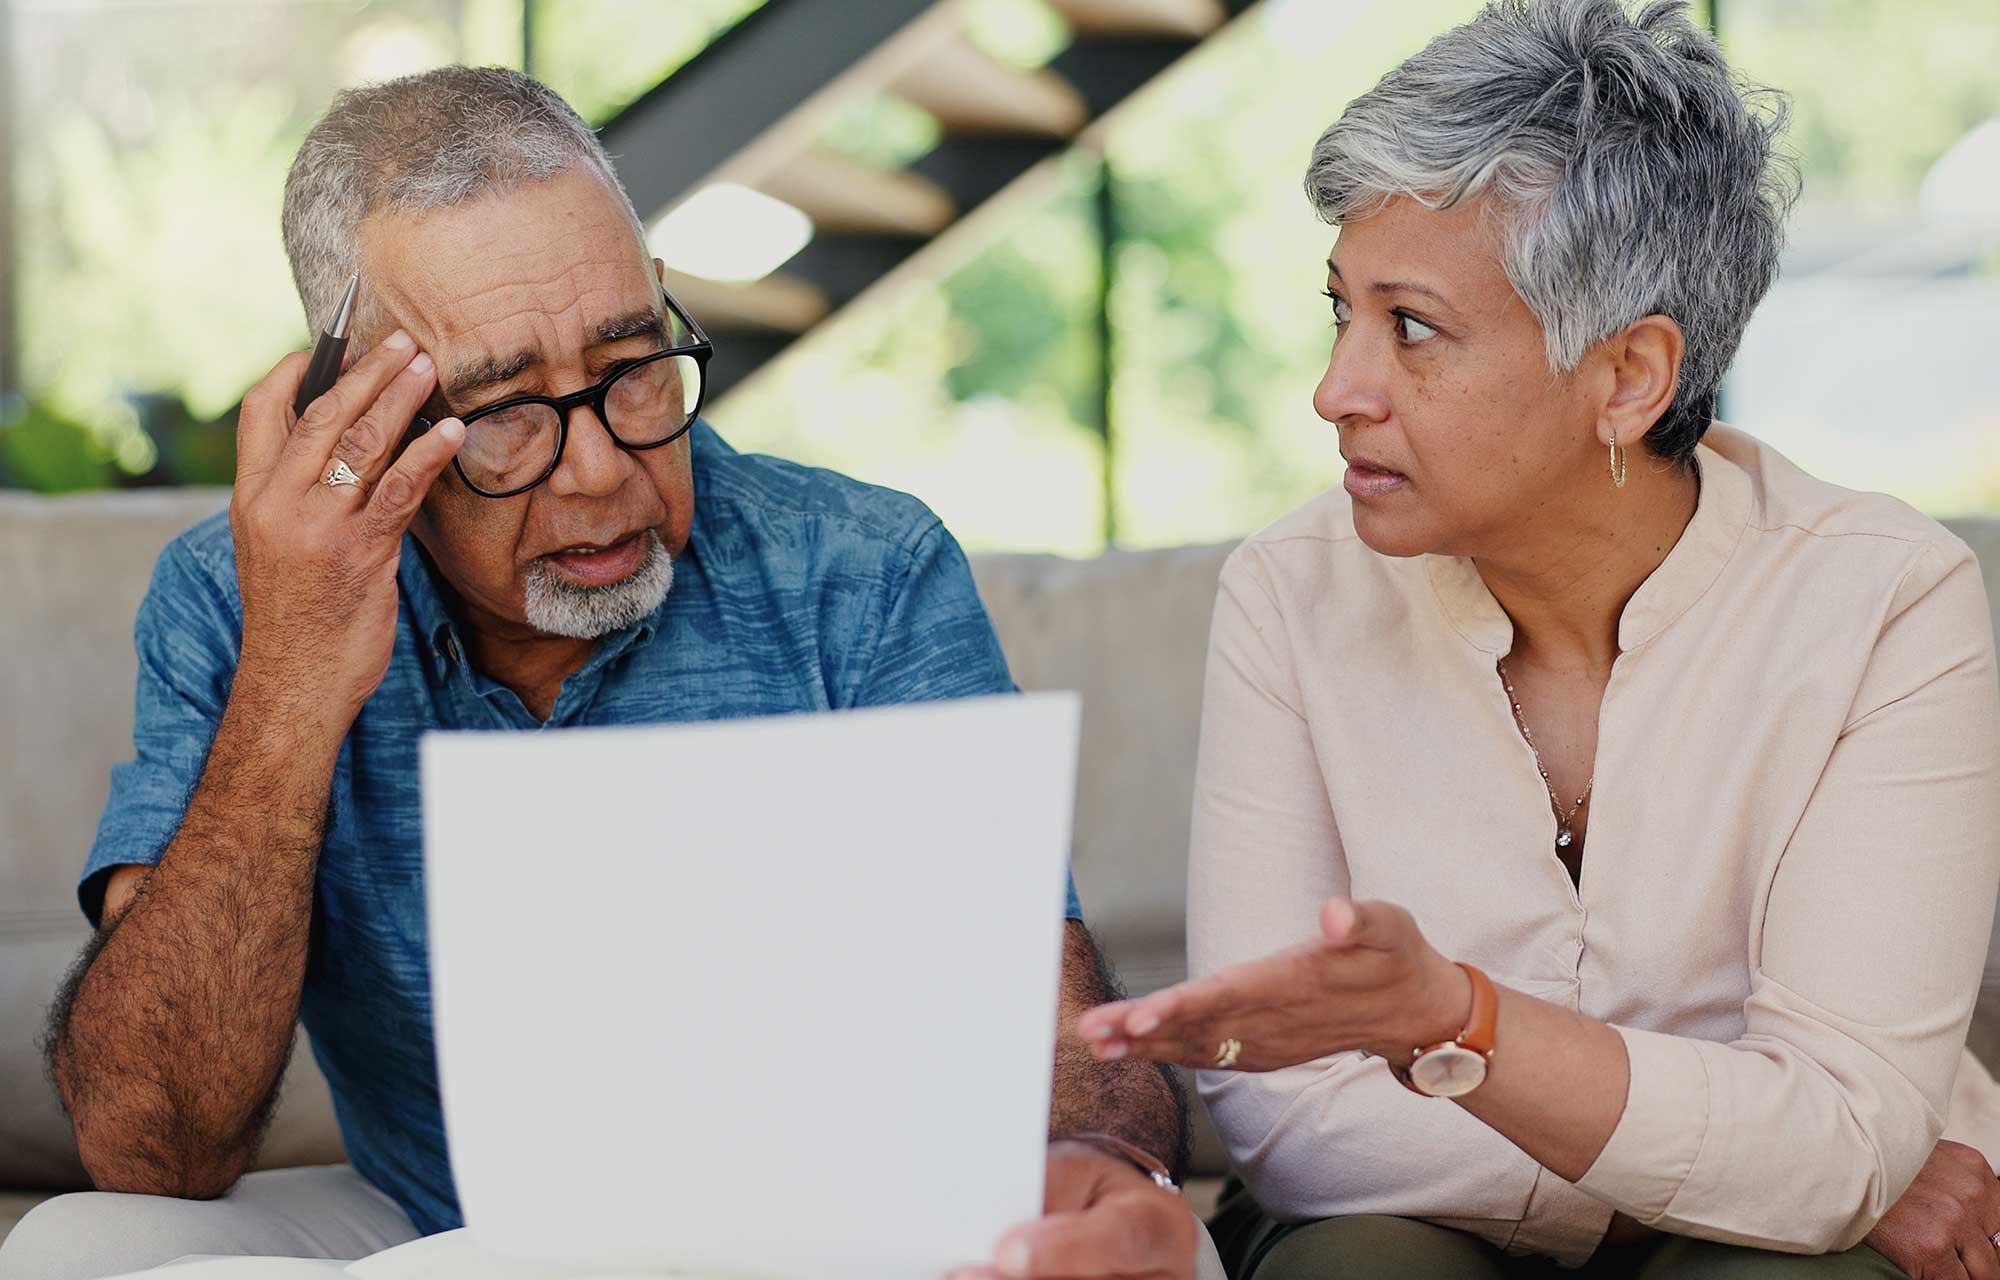
You wake up for no reason, and before you’ve even remembered what day it is, the question is already there, sitting on your chest: Do we have enough?
You lie in the dark and run the numbers you know by heart — the 401(k), the IRA, the pension if you’re lucky enough to have one, the Social Security you’re still not sure when to take. You add them up. And the strange part is, the number is usually… fine. Big, even. Bigger than your parents ever had. On paper, you did everything right.
So why doesn’t it feel like enough?
I’ve sat across the table from a lot of people who feel exactly this way, and I want to tell you something that I hope lets you exhale a little: the anxiety you feel at 3 a.m. is almost never a math problem. It’s a missing-plan problem. And those are two completely different things.
Here’s what I mean. You spent thirty or forty years being told to do one thing — save. Save more, save consistently, don’t touch it. And you were good at it. But nobody ever sat you down and answered the question that actually lets a person sleep. Not “how much do you have?” but “how much income will it reliably produce, for as long as we both live?” You have a pile of money. What you’ve never been handed is a plan that turns it into a paycheck you can count on. A pile is not a plan — and some part of you already knows that. That’s the part that wakes you up.
The number that quiets it
There is a number that answers the 3 a.m. question. It isn’t your account balance. It’s your income gap.
Take the after-tax income you actually want to live on each year. Subtract your Social Security. Subtract any pension. Subtract any other income that’s guaranteed for life. What’s left is the gap — the amount your savings has to produce, every year, no matter what the market does, for the rest of your life.
That one number changes everything, because it turns a feeling into a fact. “Do we have enough?” is unanswerable at 3 a.m. But “can our portfolio reliably produce, say, $40,000 a year, adjusted for inflation, for thirty-plus years?” — that has an answer. And an answerable question is one you can finally set down instead of carrying it around in the dark.
Why almost no one runs it
Most people never run that number, and honestly, it’s not their fault. Retirement advice is louder and more contradictory than it has ever been. One expert says annuities are the answer; the next says never touch them. The guru on the radio is certain, your brother-in-law is certain, and your neighbor did the exact opposite — and he’s certain too. So you do the reasonable thing. You wait. You read a little more. You hope it sorts itself out. And the question keeps waking you up.
We do it differently — on purpose
I didn’t come to this work from finance. I spent years in fitness, with a master’s in strength and conditioning — a field where you’re not allowed to have an opinion without the research to back it. When I moved into finance, I was stunned that the most important decisions of people’s lives were being made on gut and guru instead of evidence. So we built our firm to do the opposite.
We don’t start from an opinion about your money. We read your actual numbers against the seven risks that quietly decide a retirement — whether your income survives a bad market early, the taxes waiting in your seventies, a longer life than you planned for, and what happens to whichever of you is left. We show you where you’re solid and where you’re exposed. Then we put your current plan beside an optimal one, side by side, with the real math, and you decide. Sometimes the honest answer is “you’re in great shape — keep exactly what you have.” When that’s true, we say so.
You built it. Let’s make sure it holds.
The goal was never more products, and it certainly isn’t more worry. It’s the one thing you’ve actually been missing: a clear, honest reading of where you really stand — so the 3 a.m. question finally has an answer, and you can put it down for good.
If you’ve been carrying that question for a while, we do something called a Retirement Second Opinion. It’s a reading, not a pitch. We’ll run your income gap and read your whole picture in plain English — both spouses welcome — and you’ll leave knowing exactly where you stand, whether or not you ever work with us.
You did the hard part. Let’s make sure you can sleep knowing it’ll hold.
Book Your Retirement Second Opinion
Educational only — not investment, tax, or legal advice, and not a recommendation of any specific product or strategy. Any figures are illustrative examples, not projections or a promise of results. Annuity and insurance guarantees are subject to the claims-paying ability of the issuing carrier; not FDIC insured. Securities offered through The Quantum Group, member FINRA/SIPC. Investment advisory services offered through Summit Global Investments, a Registered Investment Adviser. Insurance products offered through Summit Income Planning Group. Separate and unaffiliated entities.