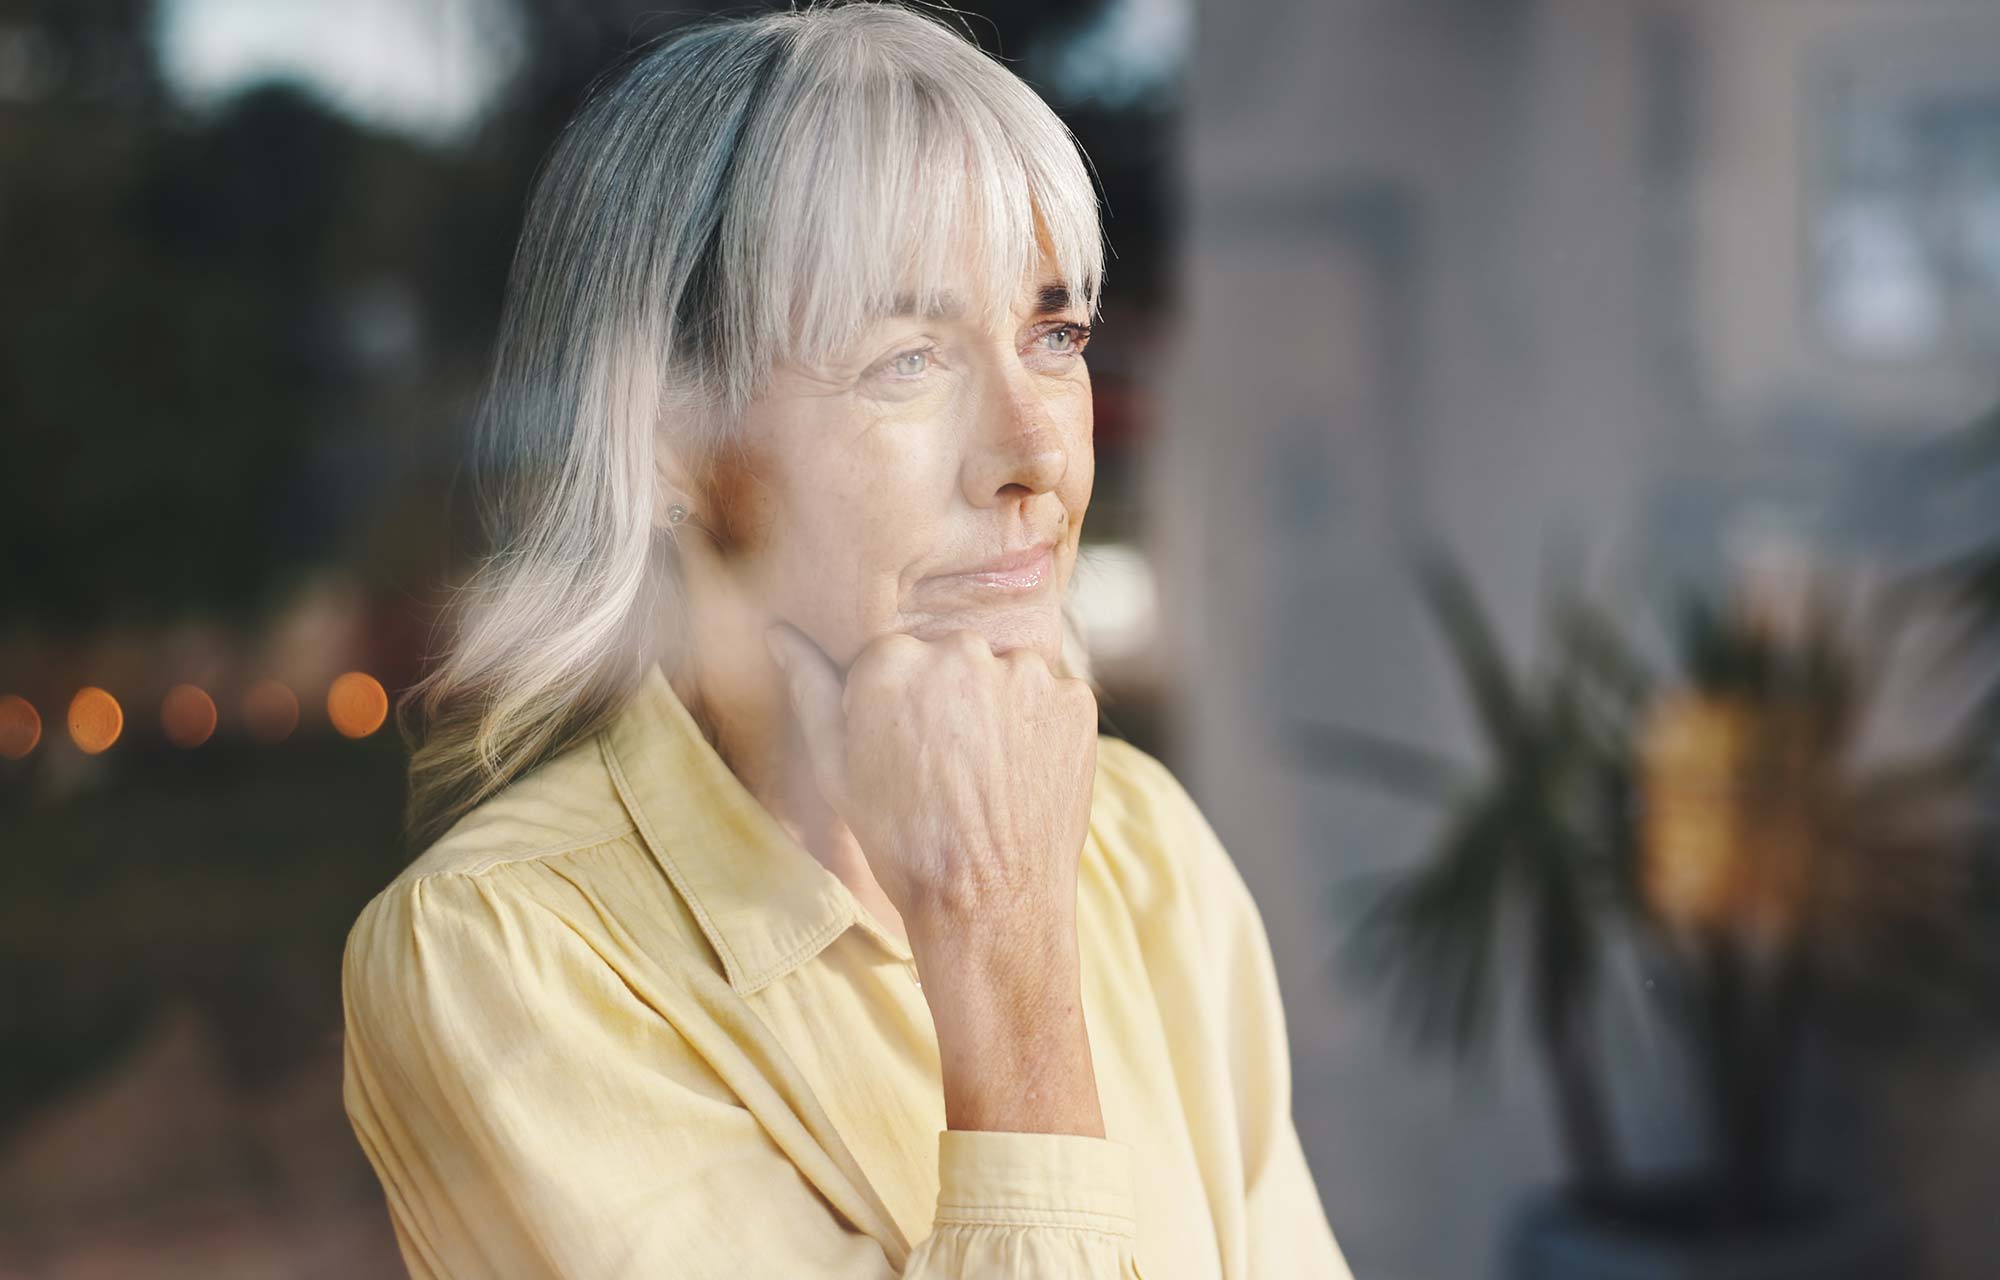
Picture the retirement party. The cake, the card everyone signed, the toast — “congratulations, you earned this.” Everyone’s smiling. And somewhere in that room, far more often than you’d guess, the person of honor is quietly terrified.
Not of retirement itself. Of running out of money.
It sounds dramatic until you see the number. In a national study, nearly two in three Americans said they are more afraid of running out of money than they are of dying. Read that again. More than death.
Why nobody says it out loud
Almost no one admits this fear, because it feels ungrateful. You have savings. You’re “supposed” to feel secure now. Saying you’re scared feels like confessing you failed at the one thing you spent forty years working toward. So people carry it silently, behind the smile, into a retirement that was supposed to be the reward.
Here’s what I want you to hear: that fear is not a character flaw, and it usually isn’t even a math problem. It’s the completely rational response to one specific gap — you have savings, but you have no paycheck.
For your entire working life, income simply appeared. Every two weeks, like clockwork. Now you’re told that paycheck stops, and instead you’ll draw from a pile that rises and falls with a market you don’t control, for a number of years no one can tell you in advance. Of course that’s frightening. Anyone thinking clearly would be uneasy about it.
The fear doesn’t need a pep talk. It needs a floor.
The antidote to that fear isn’t “try not to worry about it.” It’s structure.
The research on retirement income keeps landing in the same place: cover your essential, must-pay expenses — the housing, the groceries, the utilities, the insurance — with income that is guaranteed and doesn’t depend on the market. Then invest the rest for growth. When the bills that keep the lights on are covered by income you cannot outlive, a scary market becomes something you watch instead of something that can end you. The fear quiets because it finally has an answer standing between it and your front door.
We don’t guess at your floor — we read it
How big that floor should be, or whether you even need to build one, depends entirely on your numbers — what you spend, what Social Security and any pension already cover, and how much guaranteed income you already have. We don’t start from an opinion about that. We read your actual situation against the seven risks that decide a retirement and show you exactly where you’re solid and where you’re exposed. Sometimes the honest answer is that you already have plenty of guaranteed income and should change nothing at all. When that’s the case, we tell you.
You shouldn’t have to stand there quietly afraid
If that fear has been riding along with you — to the party, to the doctor, to 3 a.m. — you don’t have to keep carrying it. We do something called a Retirement Second Opinion: a reading, not a pitch, both spouses welcome. You’ll leave knowing exactly where you stand.
The fear fades the moment the question stops being unanswerable. Let’s get you an answer.
Book Your Retirement Second Opinion
Educational only — not investment, tax, or legal advice, and not a recommendation of any specific product or strategy. Survey figure per a national retirement study; individual results vary. Annuity and insurance guarantees are subject to the claims-paying ability of the issuing carrier; not FDIC insured. Securities offered through The Quantum Group, member FINRA/SIPC. Investment advisory services offered through Summit Global Investments, a Registered Investment Adviser. Insurance products offered through Summit Income Planning Group. Separate and unaffiliated entities.